Home & condo insurance
Coverage for the structure, your belongings and your liability, matched to how your home is built and what it would cost to rebuild it today.
See what a home policy covers.
Tap a number on the building. Each one is a coverage question Chicago owners ask, answered in plain English.
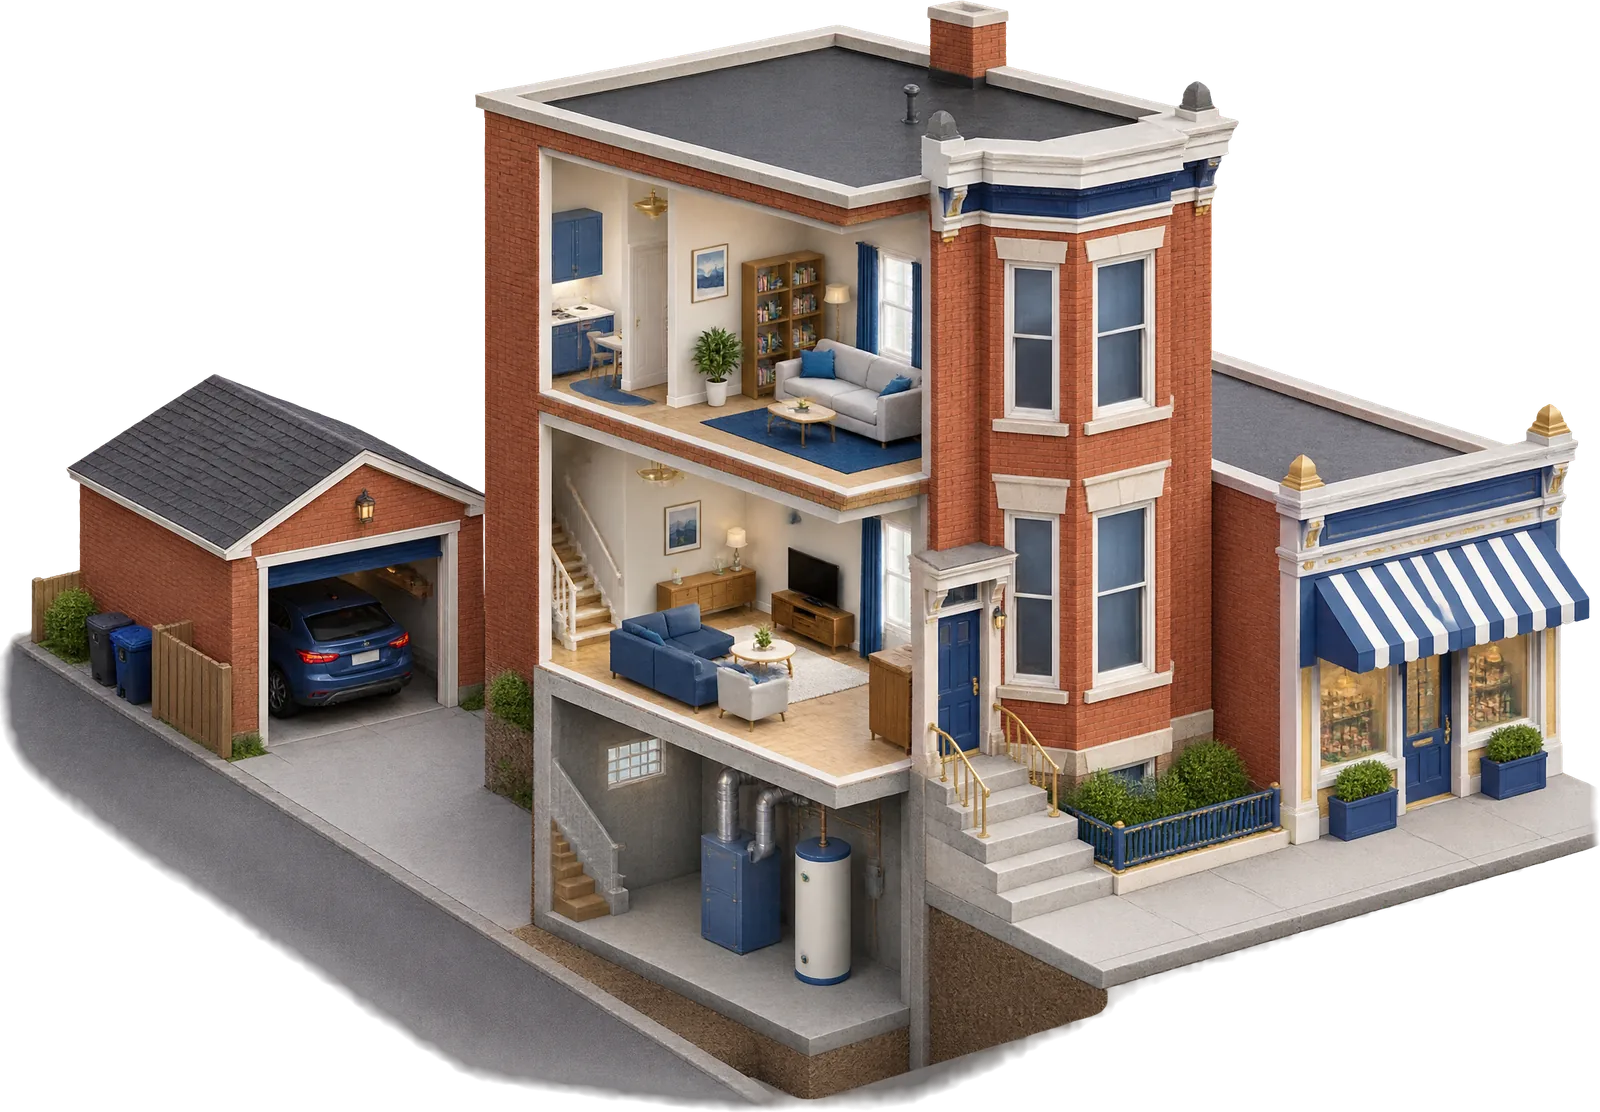
01 · Roof to foundation
Home insurance
Covers the building itself against covered losses like fire, wind and hail, along with your belongings and your liability.
02 · The upstairs unit
Renters insurance
The landlord's policy covers the building, not the tenant's things. Renters coverage protects the tenant's belongings and liability.
Renters insurance03 · The basement
Water backup
Many home policies exclude sewer and drain backup unless you add it. In a Chicago basement, ask about it before the next storm.
04 · The garage
Auto insurance
Your home policy can cover the detached garage. The car inside needs its own auto policy, and we compare those across carriers.
Auto insurance05 · The front steps
Liability & umbrella
If a guest slips on your steps, liability coverage helps with injury and legal costs. An umbrella adds a higher limit above home and auto.
Umbrella insurance06 · The shop next door
Business insurance
Property, general liability and, once there are employees, workers' compensation, placed with carriers that write main-street businesses.
Business insuranceWhat it covers
- Dwelling: rebuilding the house after a covered loss such as fire or wind
- Other structures: garage, fence, shed
- Personal property: furniture, electronics and clothing, wherever they are
- Loss of use: hotel and living costs if you cannot stay home
- Personal liability if someone is hurt on your property
- Medical payments to guests
Common add-ons
- Water and sewer backup, one of the most common Chicago-area claims
- Scheduled jewelry, art and collectibles
- Service line coverage for buried pipes and wiring
- Equipment breakdown for furnaces and appliances
Who it's for
Owners of single-family homes, two-flats and condos, first-time buyers who need a policy before closing, and anyone whose roof, furnace or claims history changed since the last renewal.
Common questions
Does homeowners insurance cover flooding?
No. Flood damage from rising water is excluded from standard policies and needs a separate flood policy. Water backing up from a sewer or sump pump is also excluded unless you add water backup coverage, which we recommend almost everywhere in Chicagoland.
Replacement cost or actual cash value?
Replacement cost pays to rebuild or replace at today's prices. Actual cash value subtracts depreciation. The difference matters most for roofs and contents, and we show you both.
My roof is 20 years old. Is that a problem?
Some carriers limit or decline older roofs; others insure them on an actual cash value basis. Knowing the age up front lets us go to the right carriers first.
Can a two-flat go on a homeowners policy?
Usually, if you live in one of the units. If you don't live in the building, it needs a landlord policy instead. Ask us and we'll tell you what fits.
Related coverage
Get a second look at your coverage.
Mon–Fri 10am–7pm · Sat 10am–5pm