Car insurance, compared.
We're an independent brokerage. Tell us about your car once and we shop the same coverage across multiple carriers, then explain the difference in plain English.
01 · The other car
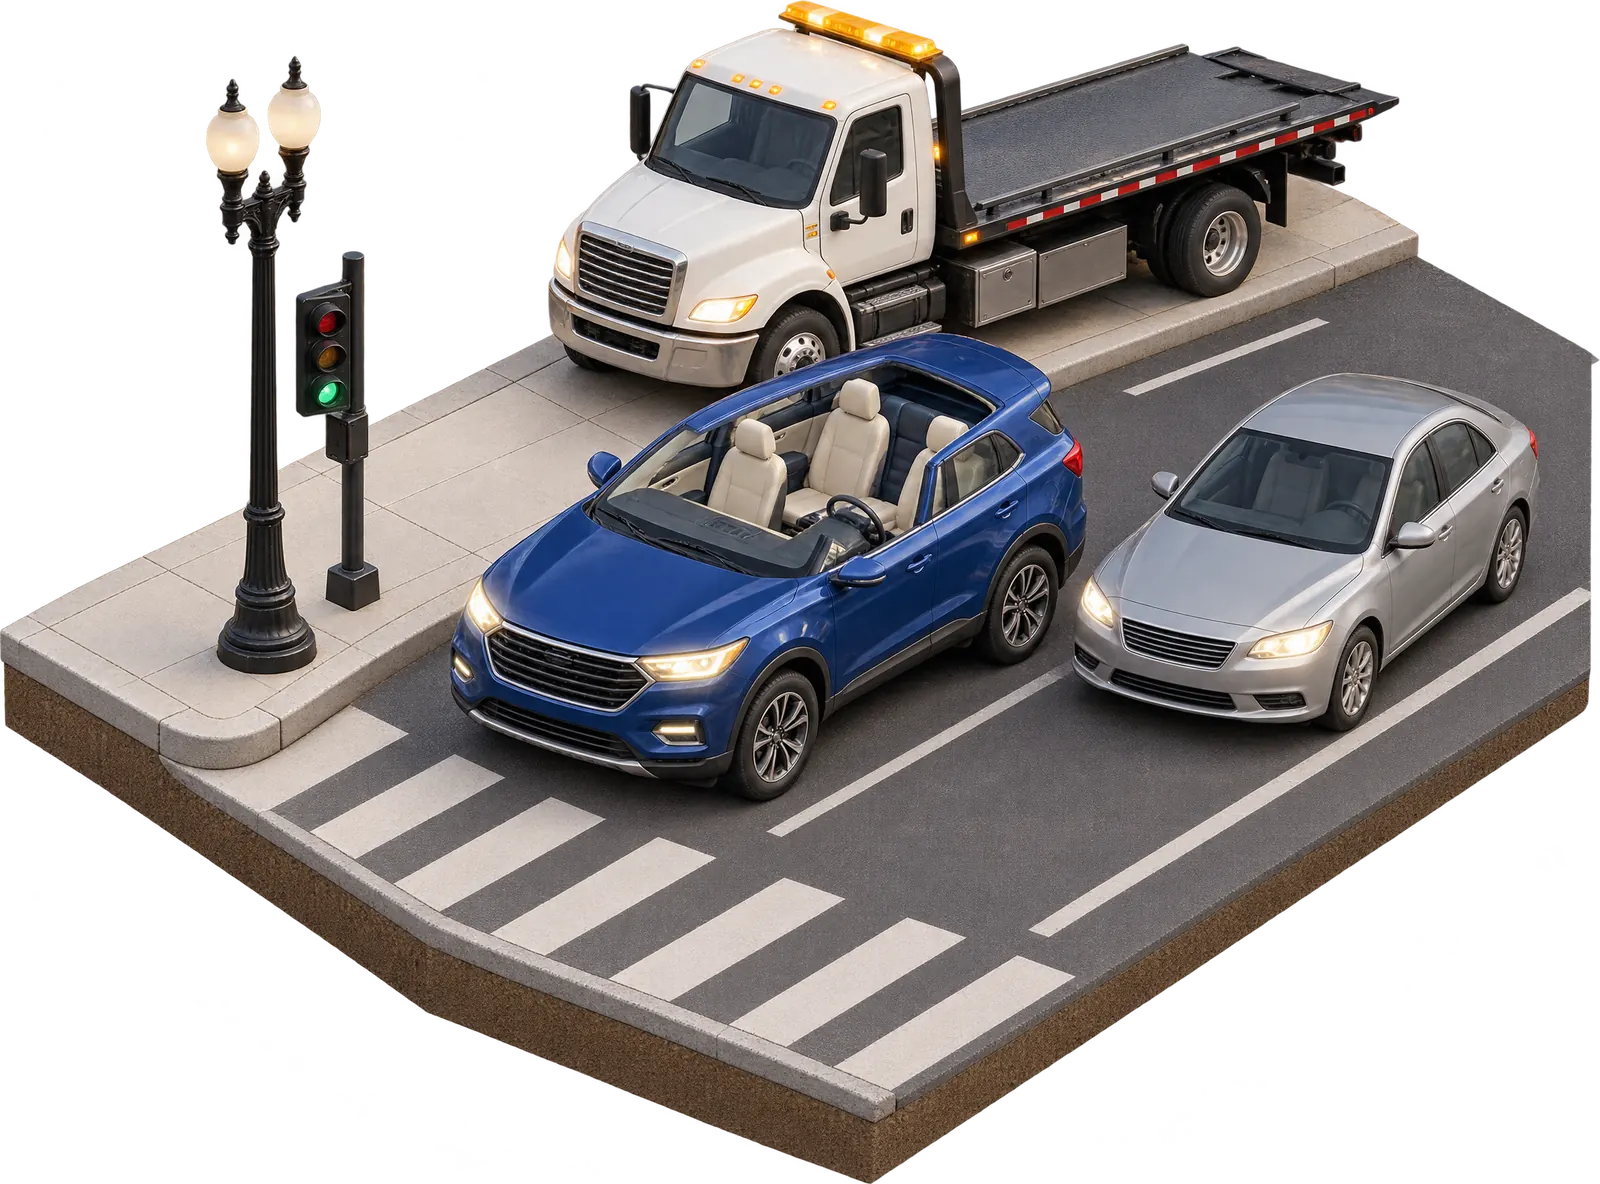
Liability
If you cause a crash, liability pays for the other driver's injuries and car, up to your limits. Illinois, Indiana and Texas all require it.
More on auto coverage02 · The front end
Collision
Pays to repair your own car after a crash, whoever is at fault, minus your deductible.
More on auto coverage03 · The windshield
Comprehensive
Theft, vandalism, hail, flooding, animal strikes and broken glass.
More on auto coverage04 · The front seats
Medical payments
Helps pay medical bills for you and your passengers after an accident, whoever is at fault.
More on auto coverage05 · The intersection
Uninsured motorist
When the at-fault driver has no insurance, this covers your injuries. Illinois requires it, and in Indiana and Texas it stays on the policy unless you turn it down in writing.
More on auto coverage06 · The tow truck
Roadside & rental
Towing and roadside help when the car won't go, and a rental while yours is in the shop.
More on auto coverageWhat each state requires.
We write auto policies in all three, and each sets its own minimum liability limits. They're the floor, not a recommendation. We'll show you what higher limits cost so you can decide with the numbers in front of you.
Illinois
liability minimum
25/50/20
injury, one person$50,000
injuries per accident$20,000
property damage
Plus uninsured motorist 25/50
Indiana
liability minimum
25/50/25
injury, one person$50,000
injuries per accident$25,000
property damage
UM and UIM unless rejected in writing
Texas
liability minimum
30/60/25
injury, one person$60,000
injuries per accident$25,000
property damage
PIP and UM unless rejected in writing
625 ILCS 5/7-203 and 7-601 · 215 ILCS 5/143a · Indiana Code 9-25-4-5 and 27-7-5-2 · Texas Transportation Code 601.072 · Texas Department of Insurance
What moves your price.
Every carrier weighs these differently. That's why the same driver can get very different quotes, and why we compare several.
- Your driving recordTickets, accidents and claims in the last few years.
- The carIts value, what it costs to repair, and its safety features.
- Where it sleepsThe ZIP code where the car is parked overnight.
- Who drives itEvery licensed driver in the household and their experience.
- Coverage and deductiblesHigher limits cost more; higher deductibles cost less.
- Your insurance historyContinuous coverage matters. A lapse can raise the price.
Whatever's in your driveway.
New and teen drivers
Adding a new driver changes the price more with some carriers than others. We compare them.
A ticket, an accident or a lapse
Usually not a dealbreaker. Some carriers specialize in exactly these drivers.
Financed or leased cars
Lenders usually require collision and comprehensive. Gap coverage handles what you would still owe after a total loss.
Uber and Lyft drivers
A rideshare endorsement fills the gap between your personal policy and the app's coverage.
Several cars, several drivers
Households with more than one car often pay less keeping them on one policy.
Vans, pickups and fleets
Vehicles used for the business belong on a commercial auto policy.
Commercial autoOne company's price, or several side by side.
A captive agent can only quote one company. We take the same car, drivers and coverage to several carriers and show you the difference.
Every pair of headlights on Lake Shore Drive is somebody's commute.
Everything else we insure.
Many carriers discount home or renters when it's bundled with auto, so it's worth quoting together.
- 07Home & condo insuranceHouses, two-flats, condos and the things inside them.
- 08Renters insuranceYour belongings, your liability and a place to stay.
- 09Umbrella insuranceExtra liability protection above your auto and home policies.
- 10Life insuranceTerm and permanent policies for the people who count on you.
- 11Business insuranceLiability, workers’ comp, commercial auto, property, professional liability and cyber.
Three steps to a clear answer.
Tell us about your car
Vehicles, drivers and your ZIP. Online in about two minutes, or call.
We shop our carriers
A licensed advisor compares the same coverage across multiple carriers and calls you with a clear recommendation.
You choose, we stay
Binding, ID cards, changes, renewals and help at claim time, from one office.
Straight answers on coverage.
Why work with an independent broker?
Understanding the difference between a captive agent and an independent broker can save you money and give you more choices.
ReadGuidesWhat to gather before you request a quote
A short checklist so your quote request is complete and we can get you accurate numbers quickly.
ReadPersonalWhen to consider an umbrella policy
Extra liability protection can be affordable and valuable. Here is when it makes sense.
ReadGet a second look at your car insurance.
Mon–Fri 10am–7pm · Sat 10am–5pm